
By Brennen Degner
As we make our way through the beginning weeks of the real estate industry’s “conference season” I thought it would be interesting to share some of the key takeaways from the litany of 30 minute “catch up” conversations that represent a majority of the schedule at each event. The three characteristics of the broader market that immediately come to mind are 1) stagnation in transaction volume 2) office is a four letter word and finally 3) the limited number of deals trying to get done are getting re-traded as though it were the new industry standard.
As far as it relates to transaction volume, we take the position (as did a majority of the individuals that I had the pleasure of connecting/reconnecting with) that the first quarter will be slow as all eyes are on the Feb/March moves the Fed makes. The consensus seems to be that we will see a couple additional modest 25bps (modest in relation to what we saw through he second half of 2022) rate increases and then we will settle in for some stability at that pricing while the Fed monitors the impact that is now making its way into the market from their 2022 activity. Once that leveling off occurs we feel that transaction volume will increase rather quickly as there is significant idle capital that needs to be put to work along with sellers sitting on the sideline waiting for capital market stability.
As far as the office comment, I am the last person to give any reliable guidance on anything office related. I have been involved in one office transaction in my entire career. However, it doesn’t take an office expert to understand the position that, unlike other asset classes, office is in the middle of not only facing the general macro headwinds the rest of us see, but more importantly because of the fact it is now a four letter word it will also experience a lack of liquidity in the capital markets. This confluence of factors leads me to believe the pain will continue until you have enough contrarian investors jump in once the basis becomes attractive enough and turn it into what we saw in retail a few years ago. Strong locations and business plans will survive, the rest will get eaten alive.
The first two points did not necessarily take a conference of like minded professionals talking in 30 minute increments to generate consensus, at least to me this was pretty obvious just watching the general pipeline and understanding differing asset fundamentals.
What I really enjoyed (I say enjoyed facetiously – we were in the midst of being re-traded as I was talking to people at IMN) was hearing different stories of pricing re-trades as we saw unprecedented volatility over 2022, especially the second half. We were not immune to the need to adjust prices while trying to close deals between July and October. This period saw the underwriting goal post for both debt and equity move on an hourly basis. I like to think we approached each in a way where we were attempting to partner to get a deal done that would result in a positive outcome for both sides. Primarily focused on transparency and communication. During this time it was not uncommon to see groups walking away from seven figure deposits. I get that these moves were necessary for transactions that might have gone under contract in Q1/Q2 of 2022 but ended up closing in Q3/Q4, as we know now those were two separate worlds. Some we found a meeting of the minds, some we didn’t, but regardless of that outcome we closed deals.
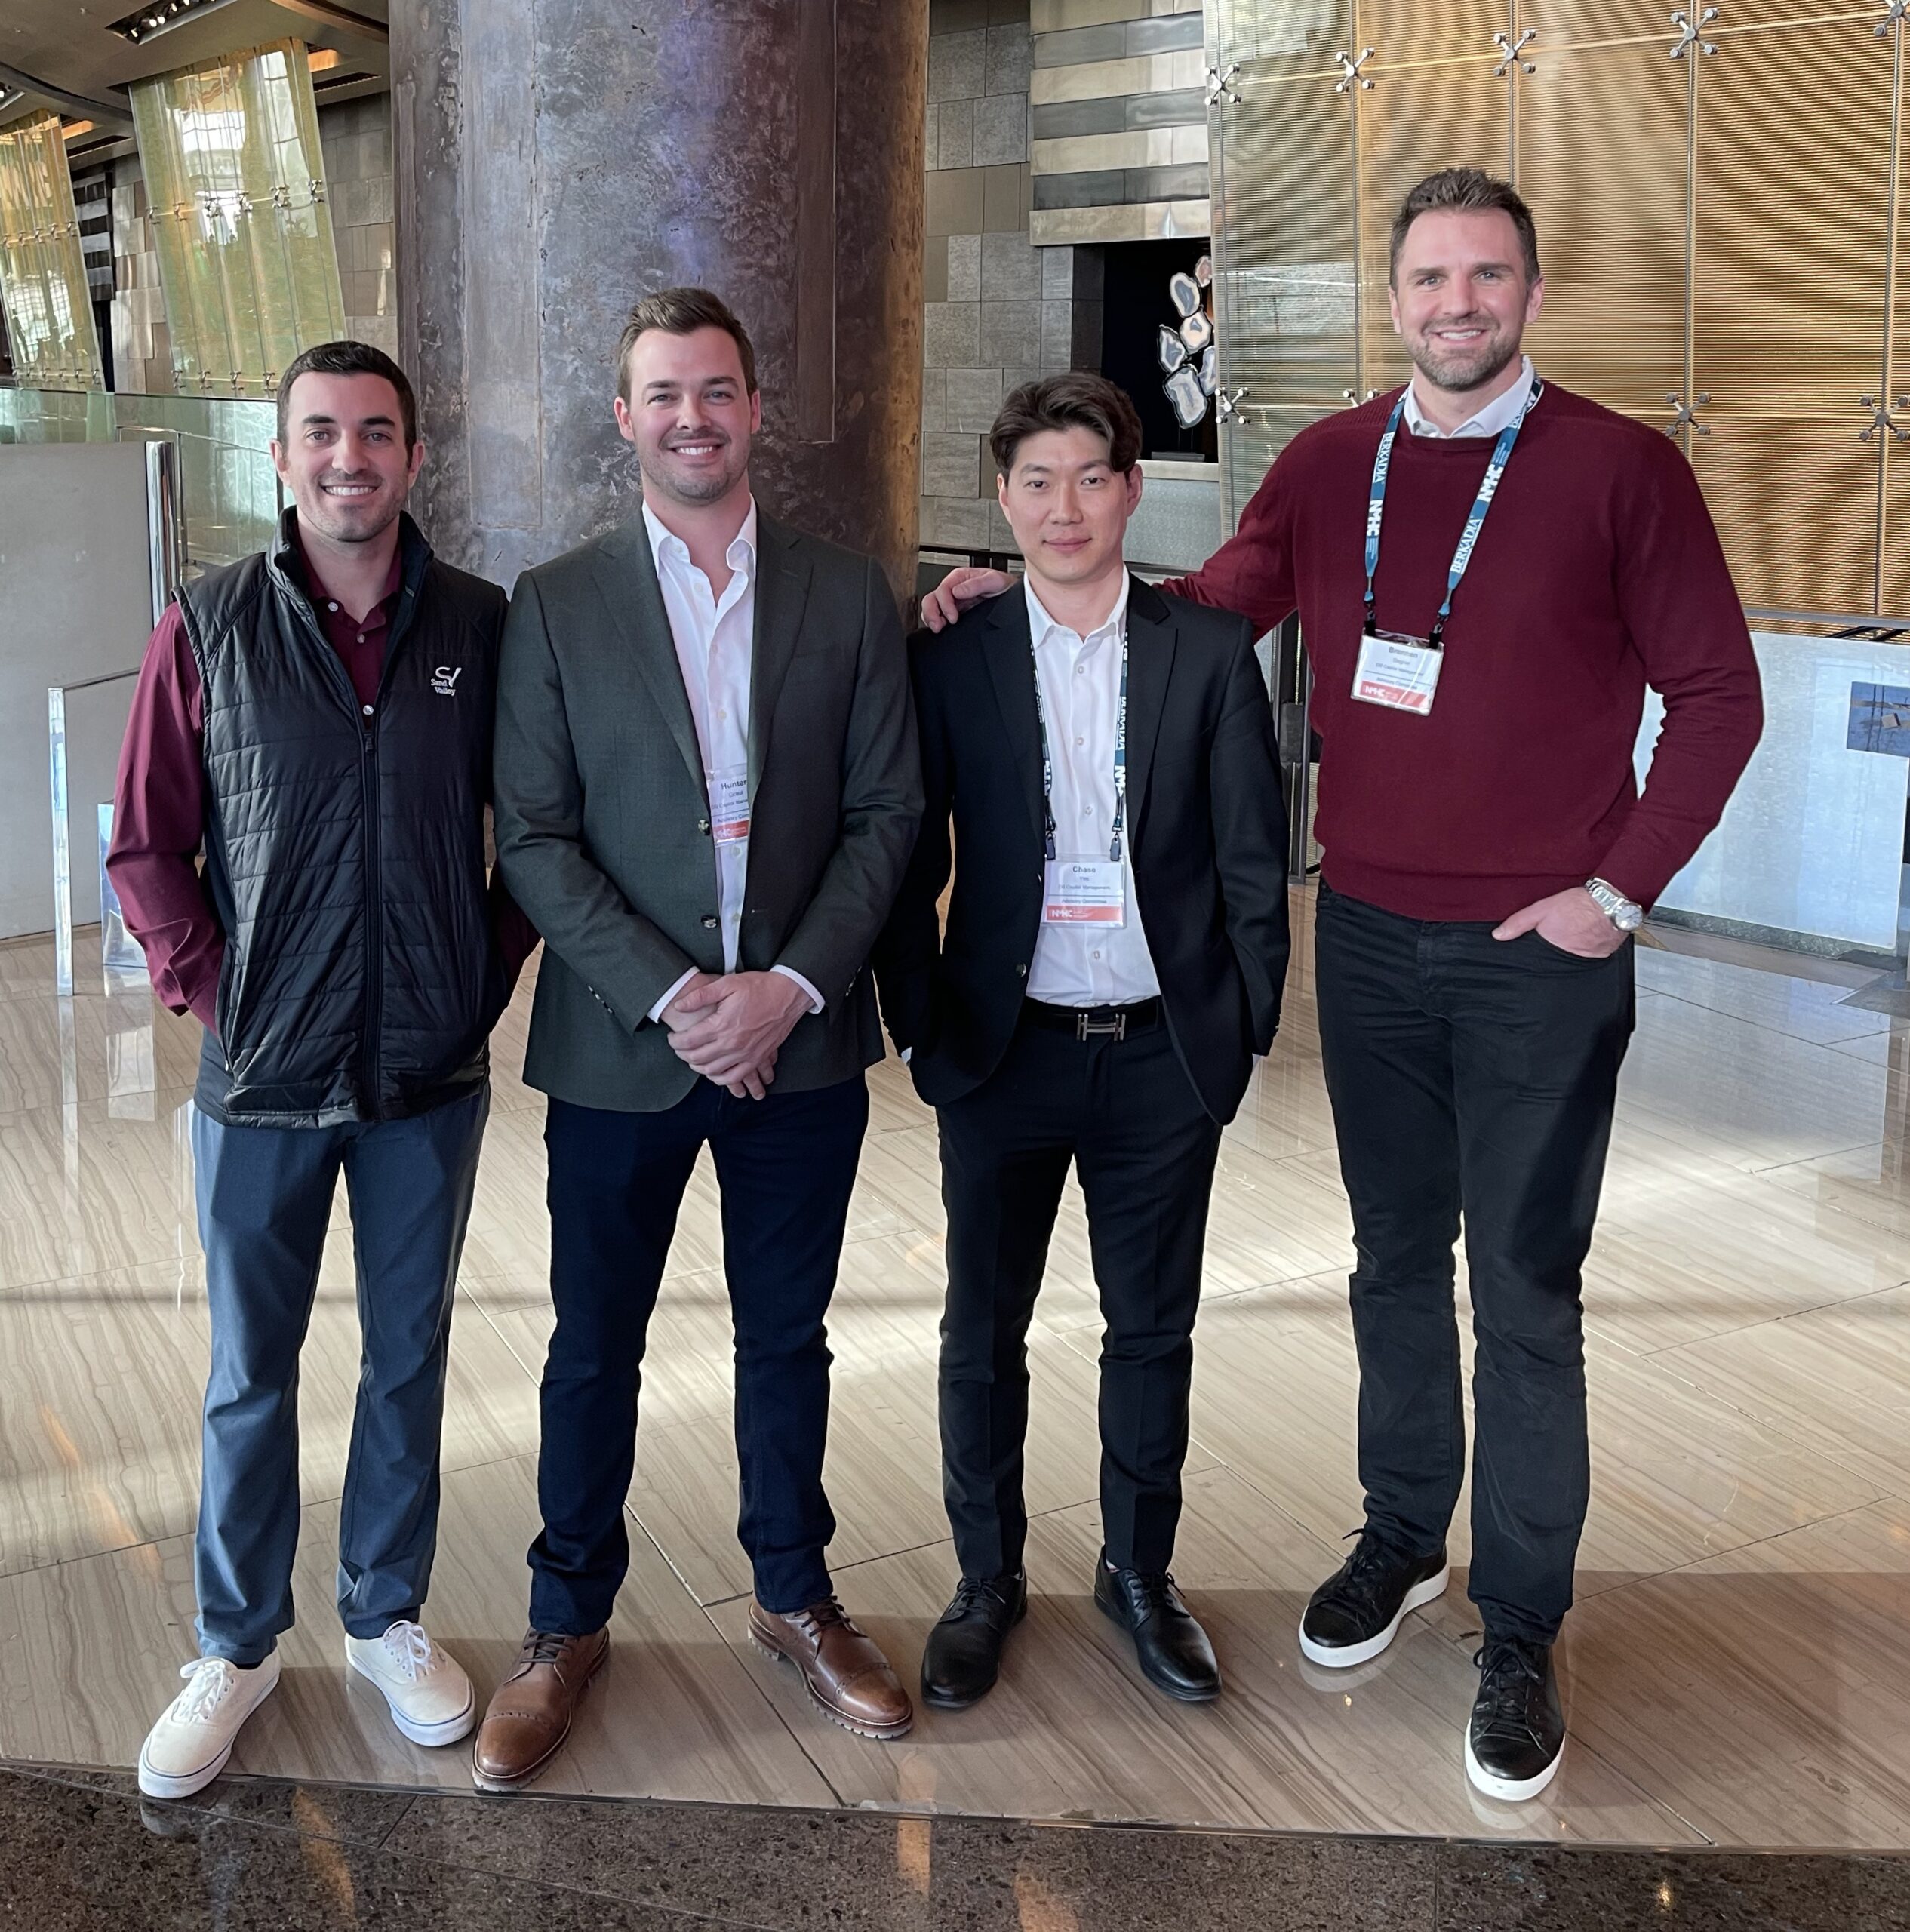
DB Capital leadership at the Annual National Multifamily House Council Meeting in Las Vegas
What surprised me the most is the number of people I spoke to that continued to experience this trend on live deals transacting between the second half of 2022 and over the first few weeks of 2023. It seems like because pricing adjustments were necessary during peak volatility, the strategy made its way into the way some groups do business. In our recent example the buyer of an asset we were selling in Provo, Utah priced the deal in October and officially put the deal under contract in early December. As a reminder over this period of time the 10 Yr Treasury dropped ~70bps. On a deal that was being financed with an agency loan this represented a major win in the capital stack. With 15 minutes to go in DD we got a letter that either acted as an amendment adjusting the price if we signed or a cancellation if we didn’t. Of course they made claims to justify their position but none of us were born yesterday. Now USC didn’t offer any classes on deal re-trading during my time as an MRED there, but I imagine this fits right in-line with what that class would look like.
I tell this story because it was such a common theme and it brings me to my key takeaway from catching up with so many peers I admire in our industry. Now more than ever it is vital to vet and truly understand the business plan, capital structure, decision makers and closing track record of who is sitting on the other side of the table. We had heard of the buyer before but didn’t do nearly a good enough job of lifting the hood on how they were going to execute. When the market is going up like a hockey stick you have hard money day one, back up buyers nipping at the heels of their competitor to step into their position, and the infamous broker threat of blacklisting a group that does not perform on your side. When that isn’t the case, knowing the relationship you are about to partner with to expend time and resources on consummating a transaction is exponentially more important.
Thanks for the read and happy deal hunting!
By Brennen Degner
Getting a chance to sit down and reflect on all that has happened in 2022 has been an enlightening experience. We often live our lives in such a day to day vacuum that it is easy to lose sight of how much has changed and what was accomplished over a year long period. Overall, 2022 was an overwhelmingly successful year for the DB team. I am proud of the growth I have seen from our team members, their deduction to the Mission, and most of all their ability to fight through adversity in a changing market. A big thank you and shout out to the teams at DB Capital, Peak Renovations and Redstone Residential that made 2022 such an overwhelming success.
I wouldn’t be speaking in true form if I didn’t focus my reflection on how and where we stand to make improvements. In the words of Ray Dalio, “pain plus reflection equals progress”, and 2022 came with a fair amount of pain. Similar to many of my peers we started off 2022 on an acquisitions high from Q4 2021 with ambitious expectations for 2022. With a healthy pipeline we saw the opportunity to continue growth at an exponential pace but could see choppiness in the waters ahead. Fundamentals in our markets were strong but it was clear that the capital markets tide was about to shift. Although we expected markets to change, we had been forecasting the same for years, I would be lying if I said we predicted the velocity and order of magnitude in which that change actually occurred.
Our Mission is, “to be the leading multifamily investment group in each of our focus markets and always exceed our client’s expectations”, and this year each day felt like a battle to fulfill that goal. When reviewing where our team can improve I always like to break things down into what is controllable vs. uncontrollable. We cannot control things like where interest rates are going, what supply chains look like, or whether or not our properties run the risk of being impacted by new supply; variables like that we can only mitigate through research and setting up a culture focused on data driven decision making. Things that are in our control are how we communicate as a team, how we build a culture of accountability, and how we develop systems aimed at reducing our margin of error on the uncontrollable variables to the lowest possible level. In 2022 as the latter part of the year slowed down, we had the opportunity to focus on shortcomings in our organization or bottlenecks that we felt were leading us away from our Mission.
We made major structural changes in how we track business plan progress, created alignment with management and construction teams that are responsible for a large part of the success of our projects, formed a strategic partnership with a management platform we knew would significantly improve operations, and we adjusted our organizational hierarchy to solve inefficiencies we saw in how we execute our projects. All this in an effort to continue to align ourselves with our Mission and build an organization that will not just withstand challenging markets but capitalize on them.
As we look out into 2023 we see opportunity on the horizon. We expect to continue to build on the growth seen in 2022, not just the growth of the portfolio but more importantly the growth and improvement in our operating platform. With the current capital markets environment we expect to see values continue to erode and provide an opportunity to enter deals at a more favorable basis than we saw in late 2021 and early 2022. Groups that bought during those periods, ourselves included, are going to need to execute or exceed their business plans to manage their way through this value deterioration. The days of buying a deal and making money because market rents grew and cap rates compressed are long gone at this point. We see overall competition for multifamily remaining high but dissipating as groups that are not well capitalized or struggling with the constant battle that under performing deals become are naturally removed from the market. However, if you can operate well and build dry powder for 2023 and 2024 we think there will be great deals to be made. Thanks for the read and best wishes for a successful 2023!